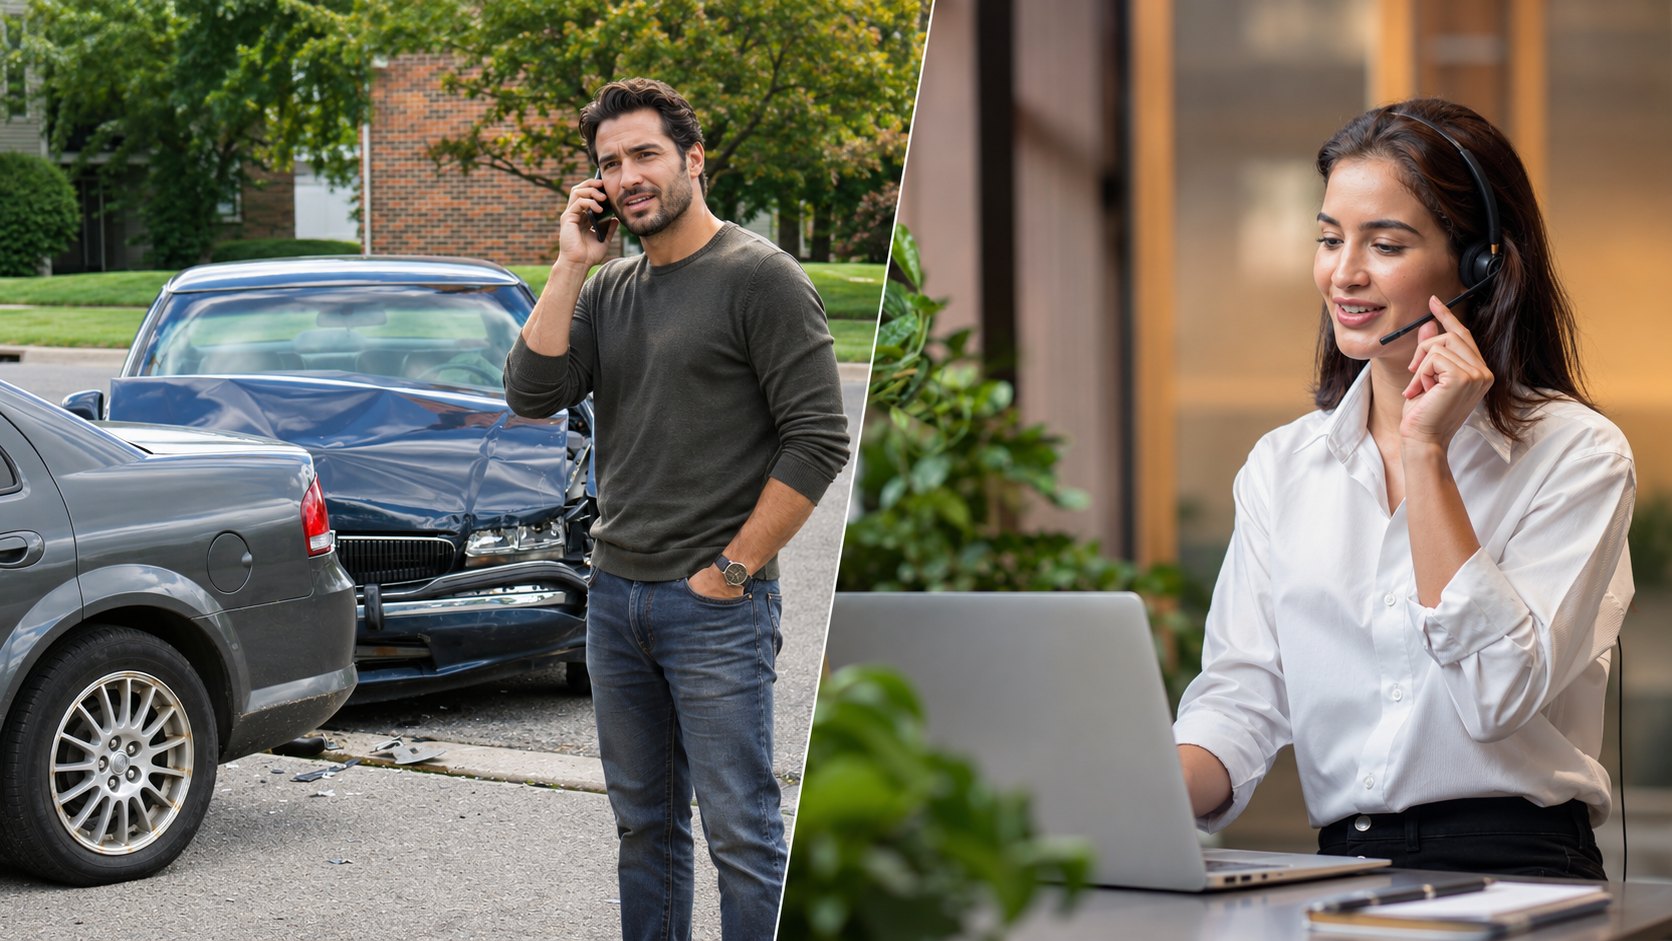
A driver on the phone after a car accident, and an agent at her desk taking the call

When something goes wrong, who do you call?

Hail on the roof. A fender-bender on 360. A pipe that bursts overnight. You call your insurance agent — and someone you know picks up.

AutoHomeBusinessLife Insurance

Who you'll call

When you call, you reach a trusted insurance expert.
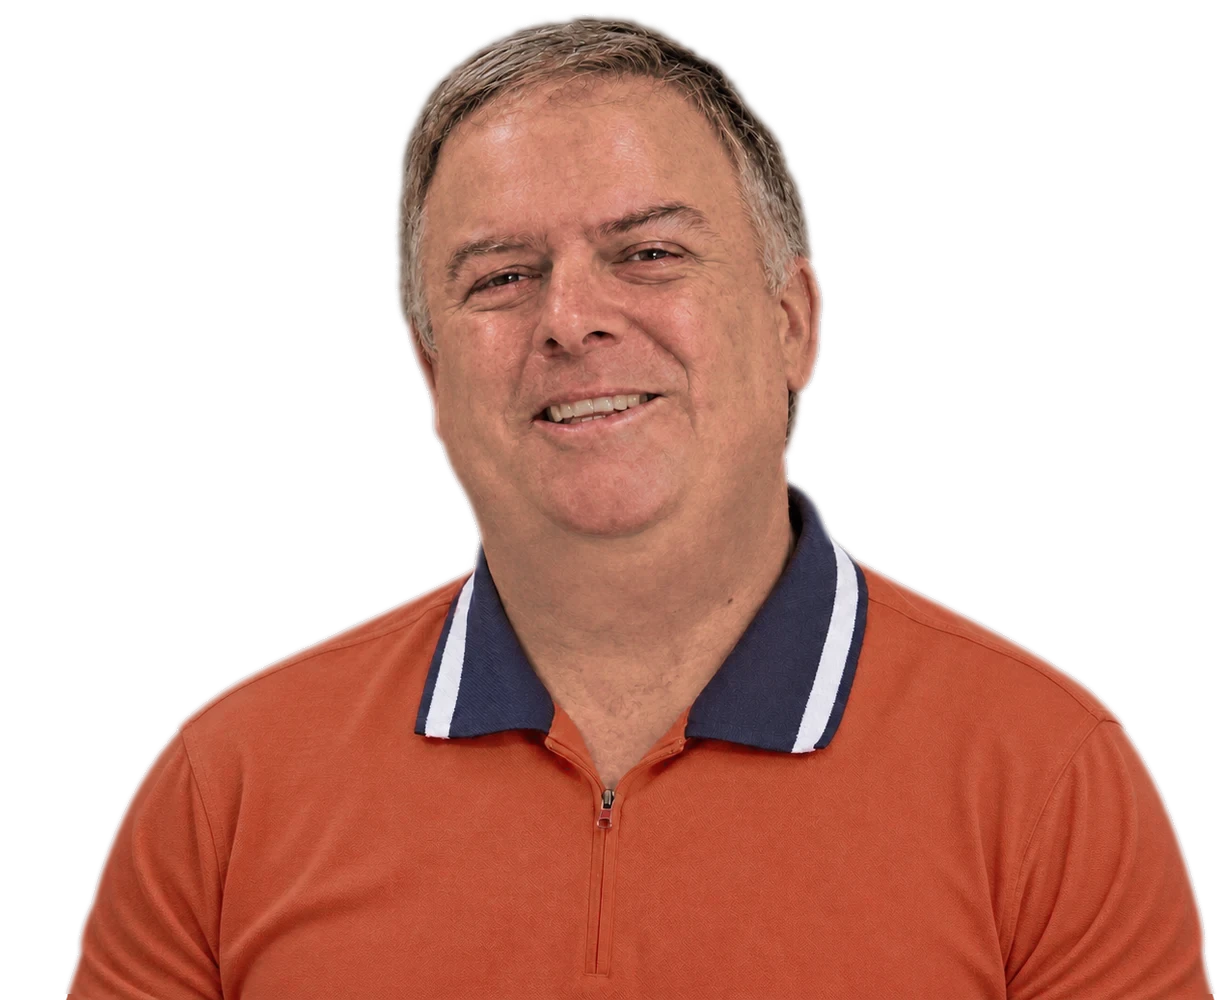
Dan Schneider, agency owner
Dan Schneider · Agency owner · Licensed Texas agent

The best time to call us is before you need us. We set up your coverage now, so when something goes wrong, you already know who to call.

  1. 01
    Call us first.We get to know you and set up the right coverage.
  2. 02
    When something happens, call or text us.You reach our office, people who know your name.
  3. 03
    We help you start your claim.We help you report it and explain what happens next.
  4. 04
    We review your coverage after.Once things settle, we make sure it still fits your life.
Meet the team
Assistant

Quick question before you call?

Fred is here for the quick questions, including after hours. Dan and the team are still the ones who take care of you.
Fred website assistant — interface preview Interface preview · Fred gives general information, not advice on your specific policy.
Quick answers, any hour

General questions about coverage, our office or what to have ready, whenever they come up.

Shared with our team

What you ask Fred gets back to Dan's team, so when you talk, they already know what you need.

A person when it matters

For advice on your policy or help with a claim, Fred points you to our team.

Coverage

Protecting what matters most.

Not sure where to start? Most households and businesses need a mix. Tell us what you're protecting and we'll point you to the right coverage.
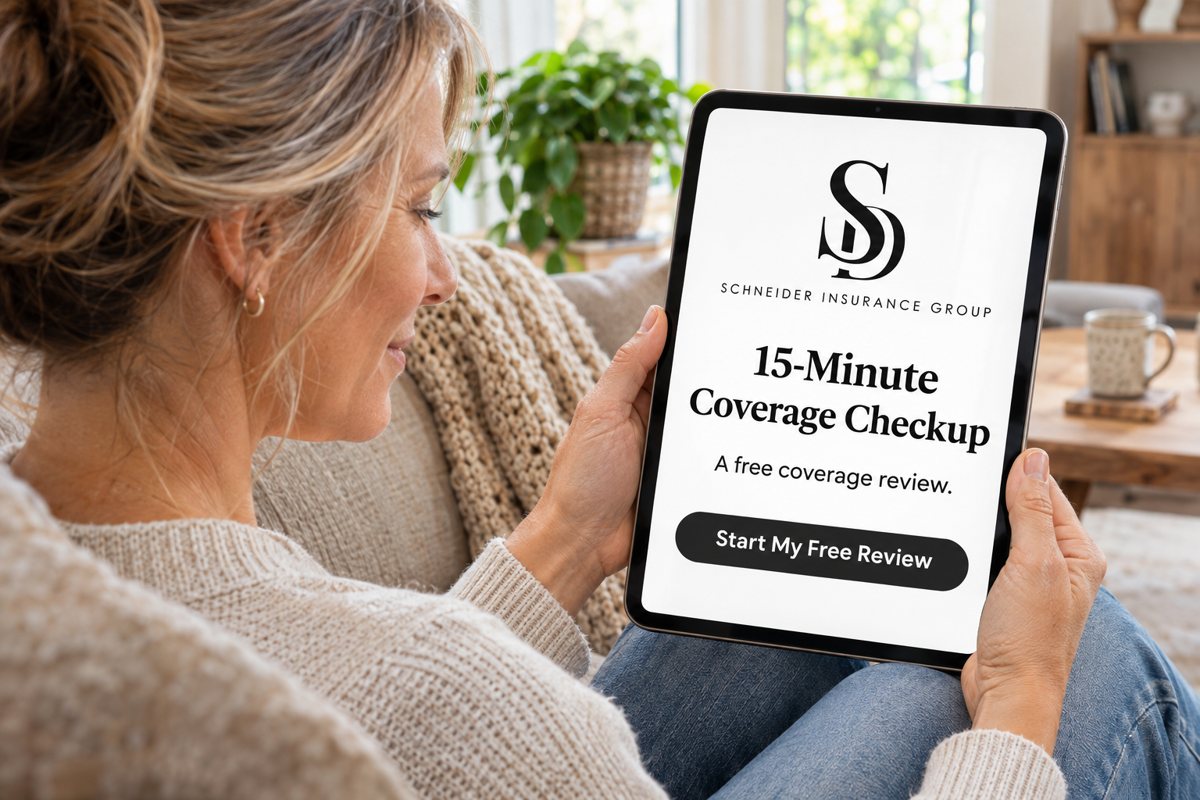
A woman at home reviewing the 15-Minute Coverage Checkup on a tablet
Free 15-Minute Coverage Checkup

New home, new car, new baby or a new business? Let's look at your coverage together.

A free, no-pressure review with our team. We go over what you have and what's changed in your life, and make sure your coverage still fits.

  • About 15 minutes, by video call, phone or in our office
  • No cost and no obligation
  • Plain-English answers to your questions
5 Stars on Google
“Dan & team are responsive, clear, and easy to work with… You can tell they care about people, not just policies.”
Jake V. · Google review
“She explained everything in a way I could understand it all… after I got off the phone with Kezia I felt so confident in not only my car coverage but for my home too.”
Brooklin G. · Google review
“Both were highly responsive by email and phone, took the time to truly understand my needs, and consistently followed through on researching the best options.”
Eileen H. · Google review
“Their honesty, service, and commitment to their clients are truly appreciated. Highly recommend!”
Tyra G. · Google review

Read all reviews on Google

In the community

We live here, too.

Pregnancy Resource Center of Grand Prairie

We hosted a diaper drive at our office. Thank you to everyone who stopped by and donated to make it a success.

Children First Golf Fun tournament

Proud sand and water sponsor for Children First Counseling Center's golf tournament. You'd find us on the 9th tee.

Based in Grand Prairie, serving clients in Arlington, Mansfield, Midlothian, Fort Worth, Dallas, Plano, Waco, Austin, Houston and across Texas.
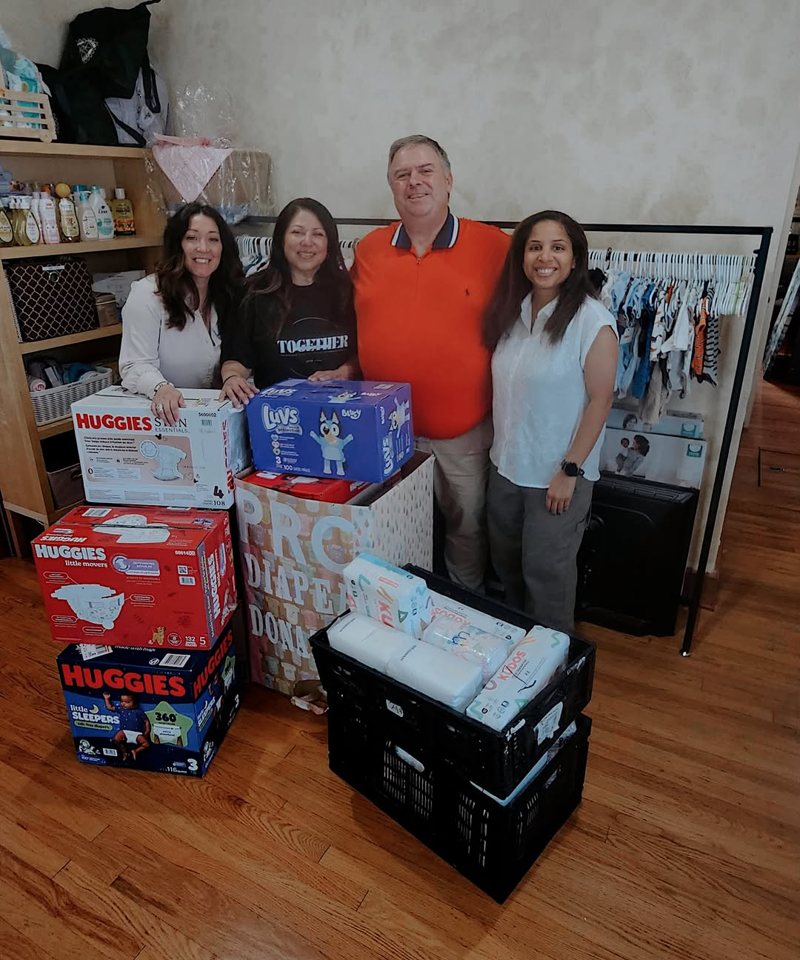
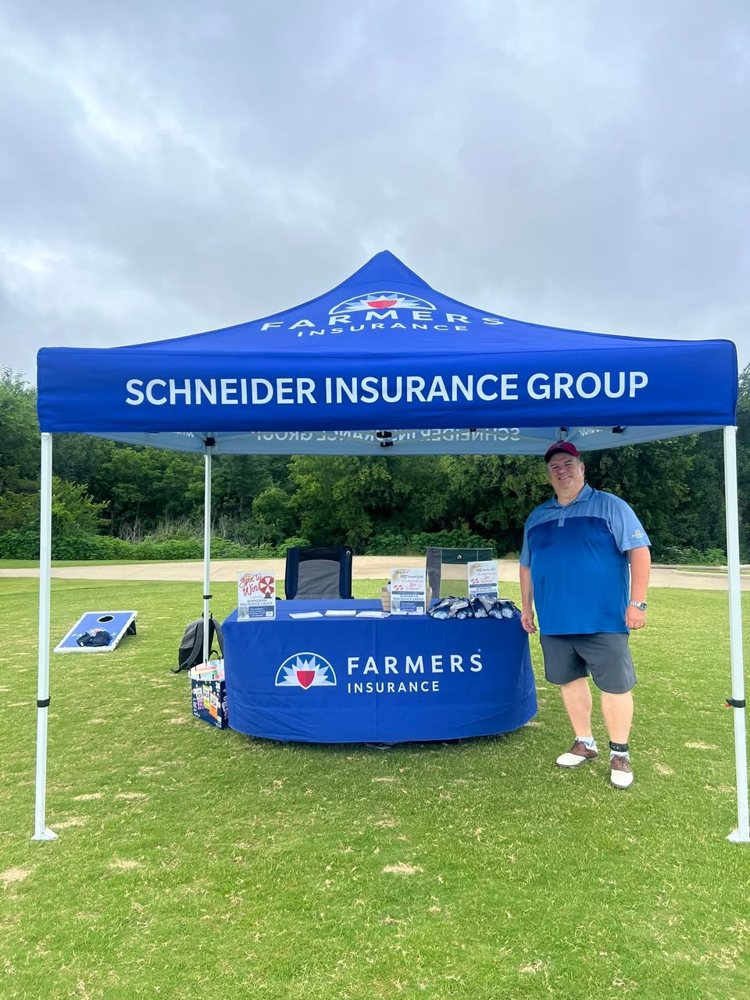
Dan Schneider with Pregnancy Resource Center staff and donated diapers Dan Schneider at the Schneider Insurance Group tent at the Children First golf tournament
Free download

The Family Insurance Organizer

Every policy, policy number and who to call, all on one page. Fill it in once, keep it in a drawer or on your phone, and you'll know exactly where everything is when you need it.

We'll email you the printable PDF. No spam, unsubscribe anytime.
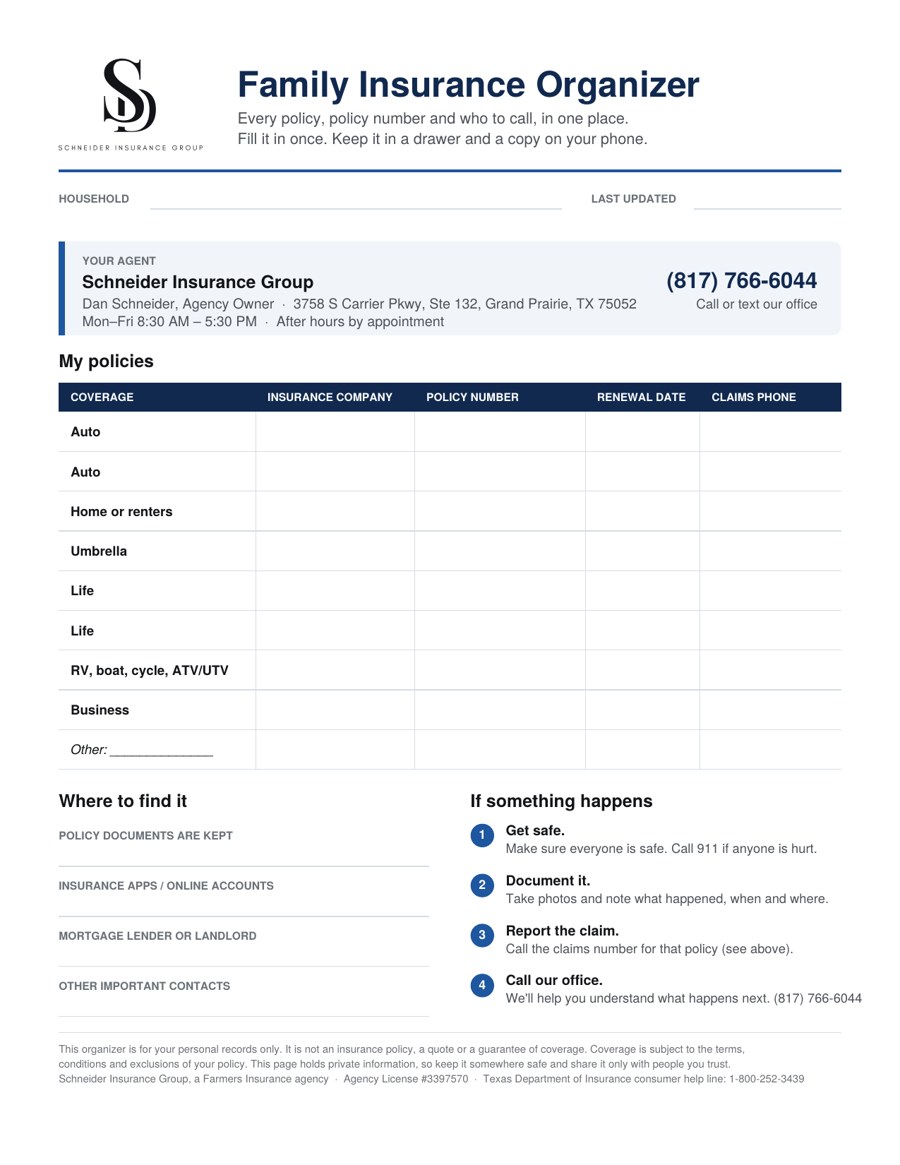
Partial preview of the printable Family Insurance Organizer
  • Find it fast when it matters. Policy numbers and claims phone numbers, all in one place.
  • Help your family help you. If you're away or unavailable, the people you trust know where everything is.
  • Stay on top of renewals. Every renewal date at a glance, so nothing sneaks up on you.
Unlock the full organizer Enter your email and we'll send you the printable, fillable PDF.
Drag to peek
FAQ

Straight answers.

General answers to common questions. Coverage depends on your policy — for yours, ask us.

What does homeowners insurance usually cover?

Most homeowners policies cover damage to your home and belongings from covered events, liability if someone is hurt on your property, and extra living costs if a covered loss forces you out. The details depend on your policy, and we can walk you through yours.

Is flood damage covered by homeowners insurance?

Flood damage from rising water is covered by a separate flood policy rather than a standard homeowners policy. Ask us whether flood coverage makes sense for your address.

What should I do right after a car accident?

Make sure everyone is safe and call 911 if anyone is hurt. Exchange information, take photos and report the claim to your insurance company. Then call us — we'll help you understand the next steps.

How much life insurance do I need?

It depends on your income, your debts and who relies on you. We'll walk through it with you, one question at a time.

See the full FAQ

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Personal Insurance

Schneider Insurance Group is here to help. Our passion is helping individuals, families and businesses protect what matters most.

Personal Insurance

In short: Personal insurance protects you, your family and the things you own: your cars, your home or rental, your recreational vehicles, and your liability if something happens.

Where to start

Not sure what you need?

  • Drive a car? Start with auto insurance.
  • Own a home? Homeowners insurance. Renting? Renters insurance.
  • Have a boat, RV, motorcycle or ATV? Add specialty coverage.
  • Want extra liability protection on top of it all? Consider an umbrella policy.
How it works with us

Three simple steps

  1. 01
    Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
  2. 02
    We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
  3. 03
    You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
FAQ

Common questions

Can I bundle my home and auto insurance?

Many insurance companies offer a multi-policy discount for insuring your home and cars together. Ask us to compare bundled and separate options.

How often should I review my coverage?

At least once a year, and any time your life changes, like a new home, car, driver or baby.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Business Insurance

Insurance solutions designed to help safeguard your business, your people and your future.

Business Insurance

In short: Business insurance protects your company from claims, property losses and interruptions. Most businesses combine a few coverages based on what they do, where they work and what they own.

Where to start

Not sure what you need?

  • Customers visit you or you work at their sites? Start with commercial liability.
  • Own or lease a space with equipment and inventory? Look at a business owner's policy (BOP).
  • Drive for work? Commercial auto.
  • Give advice or professional services? Professional liability (E&O).
  • Tools on the move or customer data on file? Inland marine and cyber.
How it works with us

Three simple steps

  1. 01
    Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
  2. 02
    We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
  3. 03
    You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
FAQ

Common questions

What insurance does a small business need in Texas?

It depends on your business. Many start with general liability and property coverage, often bundled in a BOP, and add commercial auto or professional liability if they apply.

What is a certificate of insurance?

A document that shows proof of your coverage. Clients and landlords often ask for one, and we can help you get it.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Life Insurance

Personalized life coverage built to help safeguard your family's future and provide lasting peace of mind.

Life Insurance

In short: Life insurance pays a benefit to the people you choose if you die, helping cover things like your income, mortgage, debts and future costs. Term life covers a set period; universal life is permanent coverage designed to last your lifetime.

Where to start

Not sure what you need?

  • Need coverage for a set number of years, like until the mortgage is paid off? Term life.
  • Want lifetime coverage with flexible premiums? Universal life.
  • Not sure? We'll walk through your needs together.
How it works with us

Three simple steps

  1. 01
    Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
  2. 02
    We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
  3. 03
    You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
FAQ

Common questions

How much life insurance do I need?

A common starting point is enough to replace your income for the years your family would need it, plus your mortgage, debts and future costs. We'll walk through it with you.

Can I have more than one life insurance policy?

Yes. Many people have a policy through work and their own policy alongside it.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Auto Insurance

Get the coverage you deserve.

Auto Insurance

In short: Auto insurance helps pay for injuries and damage from car accidents and other covered events. In Texas, every driver must carry at least 30/60/25 liability coverage, and many drivers add coverage for their own car, like collision and comprehensive.

Ready to drive with confidence? At Schneider Insurance Group, we make auto insurance simple and straightforward. Our team will work with you to find the right protection for the way you drive, wherever the road takes you. Contact us today.

Coverage

What's covered

LiabilityPays for injuries and property damage you cause to others, up to your policy limits.
CollisionHelps repair or replace your car after a crash with another vehicle or an object, such as a guardrail.
ComprehensiveCovers damage from things other than a collision, such as theft, fire, vandalism, hail and other severe weather.
Uninsured / underinsured motoristHelps pay your costs when the at-fault driver is uninsured or underinsured.
Personal injury protection (PIP)Helps pay medical bills, lost wages and related costs for you and your passengers, no matter who caused the accident.
Medical paymentsHelps pay accident-related medical expenses for you and your passengers, regardless of fault.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You're buying, financing or leasing a car. Lenders usually require collision and comprehensive.
  • You're adding a driver, like a teen with a new permit or license.
  • You've moved, changed cars or your commute has changed.
  • Your policy is up for renewal and you want a second look.
In Texas
  • Texas requires at least 30/60/25 liability: $30,000 for injuries per person, up to $60,000 per accident, and $25,000 for property damage.
  • Texas auto policies include personal injury protection (PIP) and uninsured/underinsured motorist coverage unless you reject them in writing.
  • Texas is an at-fault state: the driver who causes a crash is responsible for the damages.

Source: Texas Department of Insurance consumer guides.

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Driver's license numbers and dates of birth for every driver
  • Year, make, model or VIN for each vehicle
  • Where each vehicle is parked overnight
  • Your current declarations page, if you're insured now
  • Any accidents or tickets in the last few years
FAQ

Auto Insurance questions

What is the minimum car insurance required in Texas?

At least 30/60/25 liability: $30,000 for injuries per person, $60,000 per accident and $25,000 for property damage. That covers damage you cause to others. Many drivers choose higher limits and add collision and comprehensive for their own car.

Is full coverage required in Texas?

"Full coverage" isn't a legal term. Texas requires liability coverage. If your car is financed or leased, your lender will usually require collision and comprehensive too.

Does car insurance cover hail damage?

Yes, with comprehensive coverage. Comprehensive covers damage to your car from hail, theft, fire, falling objects and other non-collision events.

How do I add a teen driver?

Call us when your teen gets a learner's permit or license. Insurance companies have different rules on when a teen must be listed, and we'll walk you through the options and any discounts to ask about.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Home Insurance

Protect your home with confidence.

Home Insurance

In short: Homeowners insurance helps pay to repair or rebuild your home and replace your belongings after a covered loss, and covers your liability if someone is hurt on your property. In Texas, homeowners policies are written on forms approved by the Texas Department of Insurance.

At Schneider Insurance Group, we're here to help you protect the place you call home. With the right policy, you can rest easier knowing your home and the things in it have coverage that fits. Contact us today to learn more about our home insurance options and get a custom quote.

Coverage

What's covered

DwellingYour house itself, including the roof, walls and attached structures, for damage from covered events like fire, wind, hail and theft.
Other structuresDetached structures on your property, such as fences, sheds and detached garages.
Personal propertyYour belongings, like furniture, clothing and electronics.
Personal liabilityClaims if a guest is injured on your property or you accidentally damage someone else's property.
Loss of useExtra living costs, like a hotel or rental, if a covered loss means you can't stay in your home during repairs.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You're buying a home. Mortgage lenders require homeowners coverage.
  • You've renovated, added on or updated your roof, plumbing or electrical.
  • Storm season is coming and you want to know your deductibles.
  • You've bought valuable items like jewelry or art.
In Texas
  • Many Texas policies have a separate wind and hail deductible that's a percentage of your dwelling coverage, such as 1% or 2%. Ask us what yours is in dollars.
  • Flood damage from rising water is covered by a separate flood policy, through the National Flood Insurance Program or a private insurer. Flood policies usually have a waiting period before they take effect.
  • Homes on the Texas Gulf Coast may get wind and hail coverage through the Texas Windstorm Insurance Association.

Source: Texas Department of Insurance consumer guides.

At a glance

How a percentage wind and hail deductible works

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Your address, year built and square footage
  • Roof age and type, and any updates to plumbing, electrical or heating and air
  • Your current declarations page, if you're insured now
  • Any claims in the last five years
  • Safety features, like monitored alarms or smoke detectors
FAQ

Home Insurance questions

What does homeowners insurance cover in Texas?

Typically your house, other structures, belongings, personal liability and extra living costs after a covered loss. The details depend on your policy form, and we'll walk you through yours.

Does homeowners insurance cover hail and wind damage?

In most of Texas, including the DFW area, wind and hail are covered perils. Many policies have a separate wind and hail deductible that's a percentage of your dwelling coverage.

How does a percentage deductible work?

It's based on your dwelling coverage. With a 2% wind and hail deductible on a home insured for $300,000, you'd pay the first $6,000 of a covered hail claim.

How do I get flood coverage?

Flood coverage is written on its own policy through the National Flood Insurance Program or a private insurer. Ask us whether it makes sense for your address, and plan ahead for the waiting period.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Renters Insurance

Protection for renters.

Renters Insurance

In short: Renters insurance covers your personal belongings and your liability when you rent a house or apartment. Your landlord's policy covers the building; renters insurance covers you and your things.

Renting your home doesn't mean you have to leave your personal property unprotected. Schneider Insurance Group offers renters insurance policies designed to cover your belongings and help protect you from liability risks. Whether you're renting an apartment or a house, we can help you find the right coverage.

Coverage

What's covered

Personal propertyYour furniture, clothing, electronics and other belongings, for damage from covered events like fire and theft.
Personal liabilityClaims if someone is injured in your home or you accidentally damage someone else's property.
Loss of useExtra living costs if a covered loss makes your rental unlivable during repairs.
Medical payments to othersMedical bills for a guest injured in your home, regardless of fault.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You're renting an apartment, condo or house.
  • Your lease requires renters insurance.
  • You're moving into your first place, or moving to a new one.
  • You've added valuable items, like a new computer or jewelry.
In Texas
  • Flood damage to your belongings is covered under a separate flood policy, which renters can buy for their personal property.

Source: Texas Department of Insurance consumer guides.

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • The rental address and move-in date
  • A rough value of your belongings
  • Any high-value items, like jewelry, cameras or collectibles
  • Any liability limit your lease requires
FAQ

Renters Insurance questions

Do I need renters insurance if my landlord has insurance?

Yes, if you want your own things covered. Your landlord's policy covers the building. Renters insurance covers your belongings, your liability and extra living costs after a covered loss.

How much renters coverage do I need?

Enough to replace your belongings. A quick room-by-room home inventory is the easiest way to estimate it, and we can help you pick a limit.

Can my roommate and I share a policy?

It depends on the insurance company. Ask us whether a shared policy or separate policies fits your situation.

Can I bundle renters and auto insurance?

Many insurance companies offer a discount for insuring both together. Ask us to compare bundled and separate options.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Umbrella Insurance

Extra protection for life's surprises.

Umbrella Insurance

In short: Umbrella insurance is extra liability coverage that sits on top of the liability limits of your home, auto and watercraft policies. It's designed for larger claims and lawsuits.

Umbrella insurance offers an extra layer of protection beyond your standard insurance policies. Whether you're concerned about personal liability or want added security for your assets, Schneider Insurance Group provides umbrella insurance that adds to the liability protection you already have. With an umbrella policy, you can rest easier knowing you have an extra layer of liability protection when the unexpected happens.

Coverage

What's covered

Bodily injury liabilityLarger claims if someone is seriously injured and you're held responsible, above your underlying policy limits.
Property damage liabilityClaims for damage to someone else's property, from car accidents to a fallen fence.
Legal defenseHelp with legal costs if you're sued for damages or injuries.
Personal liability claimsDepending on the policy, claims like libel, slander and invasion of privacy.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You own a home or have significant savings or assets.
  • You have a teen driver in your household.
  • You have a pool, trampoline or host guests often.
  • You own rental property or a business.
How it works
  • An umbrella policy adds to the liability coverage you already have. It kicks in after the liability limits of your auto, home or watercraft policies.
  • Insurance companies usually require certain liability limits on those policies before they'll write an umbrella.
  • Umbrella policies are often sold in million-dollar increments.
At a glance

How an umbrella policy works

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Your current auto, home and watercraft declarations pages
  • A list of drivers in your household
  • Any rental properties you own
FAQ

Umbrella Insurance questions

What is umbrella insurance?

Extra liability coverage that sits on top of your home, auto and watercraft liability limits, for larger claims and lawsuits.

Who should consider an umbrella policy?

People with a home, savings or other assets, a teen driver, a pool or rental property. We can walk through whether it fits your situation.

Does an umbrella replace my auto or home liability?

No. It works alongside them, adding coverage after their liability limits.

How much umbrella coverage do I need?

Many people start with $1 million. The right amount depends on your assets and situation, and we'll help you think it through.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
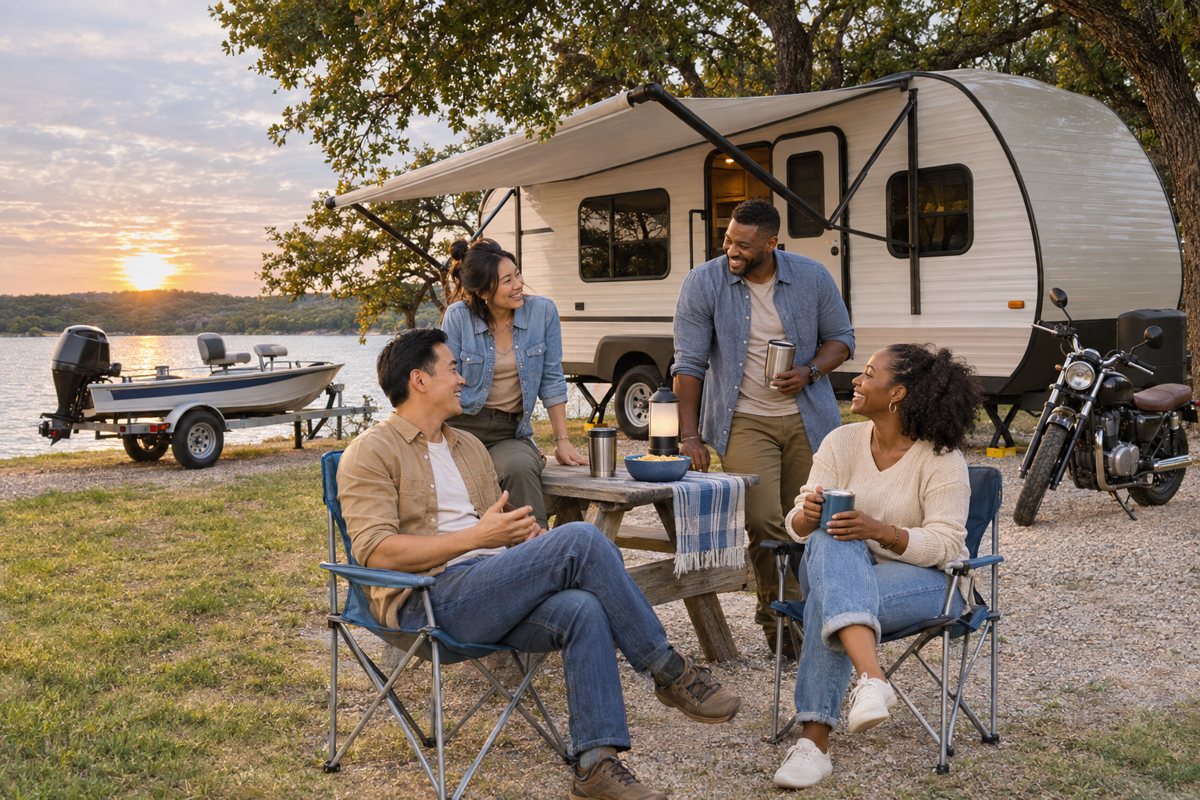
RV, Boat, Motorcycle, ATV & UTV Insurance

Adventure with confidence.

Specialty Insurance: RV, Boat, Motorcycle, ATV & UTV

In short: Specialty insurance covers recreational vehicles like RVs, boats, motorcycles, ATVs and UTVs on policies designed for how each one is used.

Your recreational vehicles deserve the same level of protection as your home or car. Whether you're cruising the open waters or hitting the road for a cross-country trip, Schneider Insurance Group offers tailored insurance policies for RVs, boats, motorcycles, ATVs, UTVs and more. We help you find the right coverage so you can enjoy every adventure.

Coverage

What's covered

MotorcyclesLiability, collision and comprehensive, uninsured motorist coverage, and options for custom parts, accessories and roadside assistance.
BoatsMost motorboats, fishing boats, pontoon boats and yachts, for collisions, property damage, bodily injury and theft. Options can include medical payments, fishing equipment and fuel spill liability.
RVsMotorhomes and travel trailers, for damage and liability on the road. Options can include vacation and campsite liability, and full-timer coverage if you live in your RV.
ATVs and UTVsDamage, theft and liability, on and off your property.
Classic and collector vehiclesOptions like agreed value based on an appraisal, and coverage while your vehicle is on display at a show.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You've bought a motorcycle, boat, RV, ATV or UTV.
  • Your lender or marina requires coverage.
  • You're planning a long trip or living in your RV full time.
  • You've customized your ride or added equipment.
In Texas
  • Motorcycles must meet the same Texas liability minimum as cars: 30/60/25.

Source: Texas Department of Insurance consumer guides.

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Year, make, model and VIN or hull ID
  • Where it's stored and how often you use it
  • Value of custom parts or added equipment
  • Safety or boating courses completed
FAQ

Specialty Insurance: RV, Boat, Motorcycle, ATV & UTV questions

Do I need separate insurance for a boat, RV or motorcycle?

Usually, yes. Each has a policy built for how it's used, so they're typically insured on their own.

Does homeowners insurance cover my ATV or UTV?

ATVs and UTVs are usually insured on their own policy, since homeowners insurance is built around your home.

What is full-timer RV coverage?

An option for people who live in their RV full time, with coverage closer to what a homeowners policy provides.

What is agreed value for a classic car?

You and the insurance company agree on the car's value up front, usually based on an appraisal.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Commercial Liability Insurance

Comprehensive protection against business risks.

Commercial Liability Insurance

In short: Commercial general liability insurance helps protect your business from claims that it caused bodily injury or property damage to someone else, including legal defense costs, up to your policy limits.

Every business faces risks, from customer injuries to property damage. That's why Schneider Insurance Group offers general liability insurance to help protect your company from costly claims and legal expenses. Coverage can help with a wide range of liability risks, so you can focus on running your business with confidence.

Coverage

What's covered

Third-party bodily injuryMedical costs and claims if a customer or visitor is hurt, like a slip-and-fall at your business.
Third-party property damageRepair or replacement costs if you or an employee accidentally damage a client's property.
Legal defense and settlementsDefense and settlement costs if you're sued, up to your policy limits.
Personal and advertising injuryClaims such as libel or slander arising from your business.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • Customers or vendors visit your location.
  • You work at clients' homes or job sites.
  • You sell products, provide services, or both.
  • A lease, contract or client asks for a certificate of insurance.
How it works
  • General liability covers claims from third parties: customers, visitors and clients.
  • Your own building, equipment and inventory are covered by commercial property or a business owner's policy (BOP).
  • Claims about professional advice or services are covered by professional liability (E&O).
Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • What your business does and how long you've been operating
  • Annual revenue and number of employees
  • Your business locations
  • Any contracts that require specific limits
FAQ

Commercial Liability Insurance questions

What's the difference between general liability and professional liability?

General liability covers bodily injury and property damage claims, like a customer slipping in your store. Professional liability covers claims that your advice or professional work caused someone a financial loss.

What is a certificate of insurance?

A document that shows proof of your coverage. Clients, landlords and general contractors often ask for one, and we can help you get it.

Is general liability included in a BOP?

Yes. A business owner's policy bundles general liability with commercial property coverage.

Does a home-based business need general liability?

If clients visit your home or you work at their locations, it's worth a look. Ask us about coverage for your setup.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
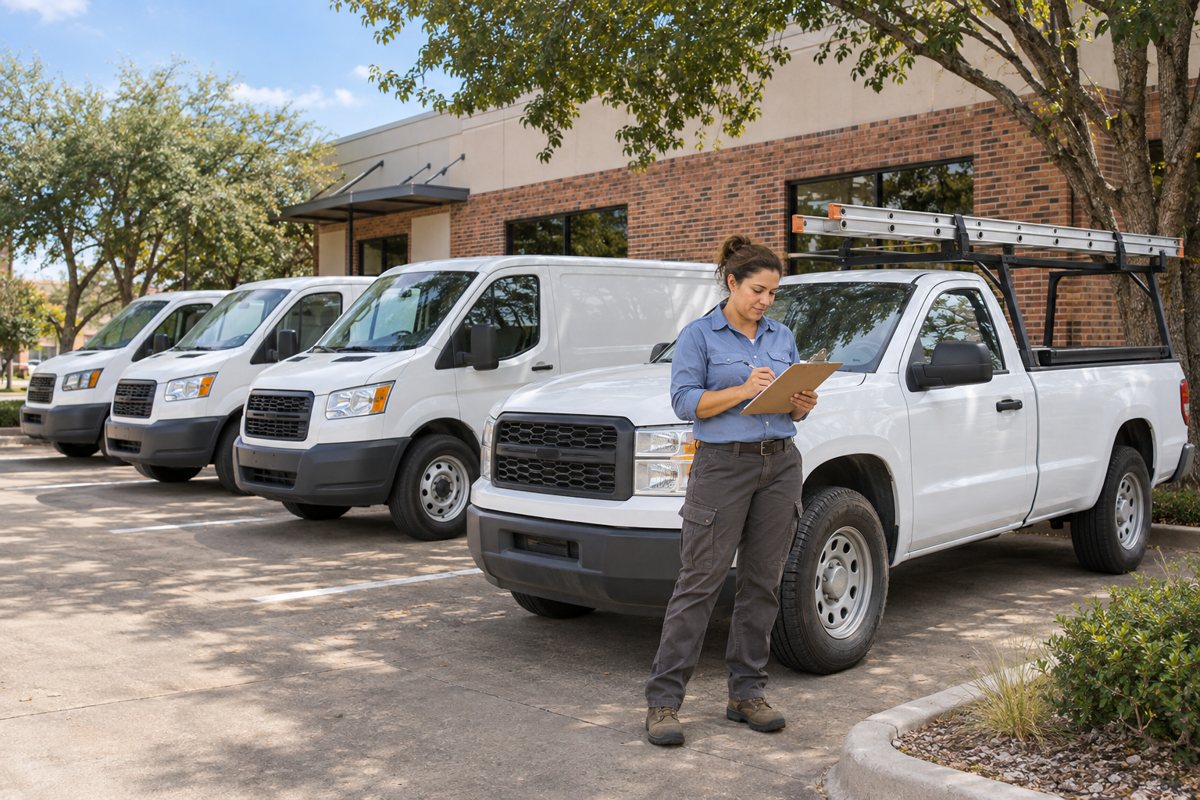
Commercial Auto Insurance

Keep your business moving forward.

Commercial Auto Insurance

In short: Commercial auto insurance covers vehicles your business owns or uses for work, including liability for injuries and damage your drivers cause and protection for the vehicles themselves.

Your business depends on reliable transportation, whether it's for deliveries, client visits or daily operations. Schneider Insurance Group provides commercial auto insurance to help protect your fleet on the road. We offer flexible coverage options designed to help protect your vehicles, drivers and business from unexpected events.

Coverage

What's covered

LiabilityInjuries and property damage to others if you or an employee is at fault while driving for work.
CollisionRepair or replacement of your work vehicle after a crash.
ComprehensiveNon-collision losses like theft, fire, vandalism and severe weather.
Uninsured / underinsured motoristYour costs when the at-fault driver is uninsured or underinsured.
Hired and non-owned autoLiability when employees use rented vehicles or their own cars for business errands.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You have one work truck or van, or a whole fleet.
  • You run delivery vans, box trucks, service vehicles, company cars or a food truck.
  • Employees drive for work.
  • A client contract requires specific auto limits.
In Texas
  • Every vehicle on Texas roads, including business vehicles, must carry at least 30/60/25 liability. Many businesses carry higher limits, and some contracts require them.

Source: Texas Department of Insurance consumer guides.

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Vehicle list with year, make, model and VIN
  • Driver list with license numbers and dates of birth
  • How the vehicles are used and how far they travel
  • Where the vehicles are parked overnight
FAQ

Commercial Auto Insurance questions

Do I need commercial auto if I use my personal car for work?

Personal auto policies are designed for personal driving. If a vehicle is owned by the business or used mainly for work, commercial auto is usually the right fit. Ask us how your use is rated.

What if employees drive their own cars for work errands?

Hired and non-owned auto coverage can cover your business's liability when employees use their own or rented vehicles for work.

Can one policy cover my whole fleet?

Yes. A commercial auto policy can list multiple vehicles and drivers.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Professional Liability (E&O) Insurance

Coverage built for today's professionals.

Professional Liability (E&O) Insurance

In short: Professional liability insurance, also called errors and omissions (E&O), helps protect businesses and professionals from claims that their advice or services caused a client a financial loss.

Professional liability insurance (PLI), often called errors and omissions (E&O) insurance, helps protect businesses and professionals from financial losses due to lawsuits alleging negligence, mistakes or failure to perform professional services. It can cover defense costs, settlements and judgments for claims like inaccurate advice or work delays, subject to your policy's terms.

Coverage

What's covered

Negligence, errors and omissionsClaims that a mistake, oversight or failure to perform a service caused a client financial harm.
Defense costsLegal defense, even if a claim turns out to be without merit.
Settlements and judgmentsAmounts owed for covered claims, up to your policy limits.
Profession-specific coverageSome professions have their own versions, such as medical malpractice or media liability. Ask us what's available for yours.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You give advice or provide professional services: consultants, real estate, design, IT, marketing and more.
  • A client contract requires professional liability.
  • A missed deadline or mistake could cost a client money.
How it works
  • Many professional liability policies are "claims-made": they cover claims made while the policy is active, for work done after the policy's retroactive date.
  • Keeping continuous coverage helps keep your retroactive date in place.
At a glance

How claims-made coverage works

Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Your profession and the services you provide
  • Annual revenue and number of employees
  • Sample client contracts, if they require coverage
  • Any prior claims
FAQ

Professional Liability (E&O) Insurance questions

What's the difference between E&O and general liability?

General liability covers bodily injury and property damage. E&O covers claims that your professional advice or work caused a financial loss.

What does claims-made mean?

The policy covers claims made while it's active, for work done after its retroactive date.

Do I need it if I've never had a complaint?

Claims can be filed even when they lack merit, and defense costs can add up. If clients rely on your advice or work, it's worth discussing.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Business Owner's Policy (BOP)

Complete small business protection.

Business Owner's Policy (BOP)

In short: A business owner's policy (BOP) combines general liability and commercial property coverage into one package for small and mid-sized businesses, with options like business interruption and equipment breakdown.

A business owner's policy (BOP) combines essential property and liability coverage into one package, with optional equipment breakdown and business interruption coverage to help protect your business from unexpected disruptions and downtime.

Coverage

What's covered

Commercial propertyYour building if you own it, plus business personal property: furniture, computers, equipment and inventory.
General liabilityThird-party bodily injury and property damage claims, including legal defense.
Business incomeLost income and ongoing expenses if a covered event, like a fire, forces you to close temporarily.
Equipment breakdown (optional)Repairs and losses when key equipment breaks down.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You run a small or mid-sized business, like an office, shop or service business.
  • You own or lease your space.
  • You have equipment, furniture or inventory to protect.
  • You run a business from home. Homeowners policies are designed for personal property, so business property is insured on its own.
Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • What your business does, revenue and number of employees
  • Whether you own or lease, and the square footage
  • Value of equipment, furniture and inventory
  • Any prior claims
FAQ

Business Owner's Policy (BOP) questions

Who qualifies for a BOP?

BOPs are designed for small and mid-sized businesses. Eligibility depends on your industry, size and risk.

Is a BOP better than buying policies separately?

A BOP bundles the most common coverages in one policy. Depending on your business, separate policies may fit better, and we'll compare both.

Does a BOP include workers' compensation or commercial auto?

No. Those are written on their own policies.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Inland Marine Insurance

Protection for your business property in transit.

Inland Marine Insurance

In short: Inland marine insurance covers business property that moves or is kept away from your main location, like tools and equipment at job sites and goods in transit over land. Despite the name, it has nothing to do with the ocean.

When your business property is on the move, it's exposed to additional risks. Schneider Insurance Group offers inland marine insurance to help protect valuable equipment, tools and merchandise as they're transported from one location to another. These policies provide specialized coverage to help protect your business assets during transit or while stored off-site.

Coverage

What's covered

Tools and equipmentTools, equipment and materials while they're transported or kept at job sites.
Goods in transitRaw materials or finished products shipped over land.
Specialized propertyHigh-value or specialized items that travel, like catering gear, artwork or contractor equipment.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You're a contractor, landscaper or tradesperson who takes tools to job sites.
  • You transport goods between locations.
  • You store equipment or materials off-site.
  • You take specialized gear to events or clients.
How it works
  • Commercial property and BOP policies are centered on your business premises.
  • Inland marine is designed for property on the move or off-site, so the two often work together.
Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • A list of tools and equipment with values
  • Where the equipment is used and stored
  • How goods or equipment are transported
FAQ

Inland Marine Insurance questions

Why is it called inland marine?

The name comes from shipping insurance. Inland marine grew out of covering goods moving over land instead of sea.

What's a contractor's equipment floater?

A common type of inland marine policy that covers a contractor's tools and equipment wherever they go.

Does it cover equipment while it's in my truck?

Inland marine is designed to cover equipment in transit. Ask us how your policy handles tools kept in vehicles.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Cyber Protection Insurance

Stay protected from digital threats.

Cyber Protection Insurance

In short: Cyber insurance helps protect your business from the financial and legal costs of data breaches, ransomware and other cyber incidents, from data recovery to legal support.

In today's connected world, businesses face increasing risks from cyberattacks and data breaches. At Schneider Insurance Group, we offer cyber liability insurance to help protect your business from the financial and legal consequences of cyber threats. From data recovery to legal support, the right policy can provide peace of mind in the digital age.

Coverage

What's covered

Data recoveryCosts to restore data and systems after an attack.
Breach responseNotifying affected customers and related services after a data breach.
Business interruptionLost income while your systems are down after a covered incident.
Cyber liabilityLegal defense and claims if customers or partners are affected by a breach.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You store customer names, addresses or financial information.
  • You take card payments.
  • Your business depends on email, computers or online systems.
How it works
  • Cyber policies often include first-party coverage, for your own costs, and third-party coverage, for claims from others.
  • Cyber risks are typically insured on a dedicated cyber policy.
Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • What kind of customer data you store and roughly how much
  • Security practices, like backups and multi-factor authentication
  • Annual revenue
  • Any prior incidents
FAQ

Cyber Protection Insurance questions

Does a small business need cyber insurance?

If you store customer information, take payments or rely on computers and email, it's worth a look.

What's the difference between first-party and third-party cyber coverage?

First-party covers your own costs, like data recovery and lost income. Third-party covers claims from others affected by a breach.

Does cyber insurance help with ransomware?

Many cyber policies include help responding to ransomware. Coverage varies, so ask us what a specific policy includes.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Term Life Insurance

Protect what matters most.

Term Life Insurance

In short: Term life insurance pays a death benefit to your beneficiaries if you die during the term of your policy, such as 10, 15, 20 or 30 years. It's often the simplest and most affordable way to provide financial support for your family.

Term life insurance pays a death benefit to your beneficiaries if you die during the term of your policy. You choose a length of time during which your policy premium won't increase, such as 10, 15, 20 or 30 years. After that level premium period, the cost of the policy increases with age until the policy expires.

Often considered the simplest type of life insurance coverage, term life can help you provide basic, more affordable financial support for your loved ones when they may need it most, such as paying off a mortgage or college tuition, if you're not there to provide for them.

Coverage

What's covered

Death benefitA payment to your beneficiaries if you die during the term.
Level premium periodA set length of time, such as 10, 15, 20 or 30 years, during which your premium won't increase.
After the level periodThe cost of the policy increases with age each year until the policy expires.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You have a mortgage or other debts.
  • People rely on your income, like a spouse or children.
  • You want to help cover future costs like college tuition.
  • You've had a major life change: marriage, a new baby or a new home.
How it works
  • We start by looking at your needs: income, debts and who relies on you.
  • You choose a coverage amount and term length.
  • The insurance company reviews your application, which may include health questions or a medical exam, and then issues your policy.
Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Date of birth and basic health information
  • Your income and major debts, like a mortgage
  • Who you'd like as beneficiaries
FAQ

Term Life Insurance questions

How much life insurance do I need?

A common starting point is enough to replace your income for the years your family would need it, plus your mortgage, debts and future costs like college. We'll walk through the numbers with you.

What happens when my term ends?

When the level premium period ends, coverage either stops or the premium rises with age each year. Some policies let you convert to permanent coverage, so check your conversion options before the term ends.

Is life insurance through work enough?

It depends on your goals. Group life through work is usually a set amount and tied to that job. Many people add their own policy alongside it.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Universal Life Insurance

Smart protection with living benefits.

Universal Life Insurance

In short: Universal life insurance is permanent life insurance designed to last your lifetime, with the flexibility to adjust your premium, payment timing and death benefit within policy limits.

Universal life insurance is a type of permanent life insurance with more flexibility than whole life insurance, because you can change the premium you pay, the timing of your payments and your death benefit while your policy is in effect. It is designed to last your lifetime and, like all life insurance, is there to help you support your loved ones' financial future.

As your needs and priorities change, a universal life insurance policy lets you adjust your coverage and premiums, within policy limits.

Coverage

What's covered

Lifetime death benefitCoverage designed to last your whole life, as long as the policy stays in force.
Flexible premiumsYou can change how much you pay and when, within policy limits.
Adjustable death benefitYou can adjust your coverage as your needs and priorities change, within policy limits.
Cash valueUniversal life policies build cash value over time.

Coverage depends on your policy's terms, conditions and exclusions. We'll walk you through yours.

Who it's for

When to get it

  • You want coverage that lasts your lifetime, not just a set term.
  • You want flexibility to adjust payments as your finances change.
  • You're planning for long-term needs, like final expenses or leaving something for loved ones.
How it works
  • Universal life has more flexibility than whole life insurance, because you can change your premium, payment timing and death benefit while the policy is in effect.
  • Changes are made within the limits of your policy, and we'll help you understand how they affect your coverage.
Getting started

How to get covered with Schneider Insurance Group

01Tell us what you need.Call or text (817) 766-6044, book a video call, stop by the office or request a quote online.
02We review your options.We explain coverages, limits and deductibles in plain English so you can compare with confidence.
03You choose. We stay with you.Once you're covered, we're here for questions, changes at renewal and help starting a claim.
What to have ready
  • Date of birth and basic health information
  • Your long-term goals for the coverage
  • Who you'd like as beneficiaries
FAQ

Universal Life Insurance questions

What's the difference between universal and term life?

Term life covers you for a set number of years. Universal life is permanent coverage designed to last your lifetime, with flexible premiums and an adjustable death benefit.

What's the difference between universal and whole life?

Both are permanent. Universal life offers more flexibility to change your premium, payment timing and death benefit while the policy is in effect.

Can I change my universal life premium?

Yes, within the limits of your policy. We'll help you see how a change affects your coverage.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Our Team

A reputation built on reliability.

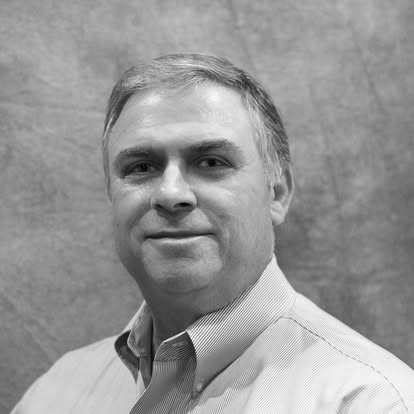
Dan Schneider, agency owner
Dan Schneider · Agency owner · General lines insurance

About Schneider Insurance Group

As an agency owner, I lead a team of dedicated professionals at Schneider Insurance Group, focused on delivering tailored insurance solutions that meet both personal and commercial needs. My role centers on designing customized coverage programs, aligning the right products with each client's goals, and serving as a trusted liaison between clients, partner agencies and underwriters to ensure a seamless, transparent experience from start to finish.

My mission is to combine strategic marketing insight with a deep commitment to client-focused service, creating insurance solutions that are not only comprehensive but truly practical and responsive to real-world needs. My background in business development shapes my approach to building strong relationships, navigating complex challenges, and creating long-term value through thoughtful risk management and well-structured insurance strategies.

At Schneider Insurance Group, we don't just sell policies. We work to make sure you are properly insured, confidently protected and supported at every stage of your journey.

Role
Agency owner · General lines insurance
Education
Northern Illinois University
Serving
Grand Prairie, Dallas–Fort Worth and clients across Texas
Grand Prairie Chamber of Commerce
Rooted in Grand Prairie

Proud member of the Grand Prairie Chamber of Commerce. [Confirm current membership]

The team

The people you'll talk to.

Photo

Stephanie Jumper Schneider

[Role to confirm]

Photo

Kezia Collins

[Role to confirm]

Photo

[Team member]

[Role to confirm]

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30
Insurance Questions, Answered

Straight answers to the questions Texans ask about auto, home, business and life insurance, from our Grand Prairie team.

Working with a local agent

Is there a local insurance agent in Grand Prairie, TX who can help with home and auto insurance?

Yes. Schneider Insurance Group is a Farmers Insurance agency at 3758 S Carrier Pkwy, Ste 132, in Grand Prairie, TX. We help individuals, families and businesses with auto, home, renters, umbrella, specialty vehicle, business and life insurance. Call (817) 766-6044, Monday through Friday, 8:30 AM to 5:30 PM.

Back to home →

Should I use an insurance agent or just buy insurance online?

Buying online can be quick, but an agent can help you understand what you're buying, match your coverage to your needs and help when you need to file a claim. With a local agent you also have a person to call when something goes wrong, instead of starting over with a call center.

Back to home →

How do I get an insurance quote from Schneider Insurance Group?

Call (817) 766-6044, stop by the Grand Prairie office or send a request through our contact page. For a quote, have your current policy (if you have one), driver and vehicle details for auto, or your address and home details for homeowners.

Contact us →

Can I bundle my home and car insurance to save money?

Often, yes. Many insurance companies offer a multi-policy discount when you insure your home and cars together. How much you save depends on the company and your situation, so ask us to compare bundled and separate options.

Home Insurance →

How often should I review my insurance coverage?

At least once a year, and any time your life changes: you buy a home, add a driver, get married, have a baby, start a business or make a big purchase. A quick review keeps your coverage matched to your life.

Contact us →

Auto insurance in Texas

What is the minimum car insurance required in Texas?

Texas requires at least 30/60/25 liability coverage: $30,000 for injuries per person, up to $60,000 per accident, and $25,000 for property damage. That's the legal minimum, and it covers damage you cause to others. Many drivers choose higher limits and add coverage for their own car, like collision and comprehensive.

Auto Insurance →

Is full coverage car insurance required in Texas?

No. "Full coverage" isn't a legal term. Texas only requires liability coverage. But if your car is financed or leased, your lender will usually require collision and comprehensive coverage too.

Auto Insurance →

Do I need PIP and uninsured motorist coverage in Texas?

They aren't required, but Texas auto policies include personal injury protection (PIP) and uninsured/underinsured motorist coverage unless you reject them in writing. PIP helps pay medical bills and some lost income no matter who is at fault. Uninsured/underinsured motorist coverage helps if the other driver is uninsured or underinsured.

Auto Insurance →

Does car insurance cover hail damage in Texas?

Yes, with comprehensive coverage. Comprehensive covers damage to your car from things other than a collision, such as hail, theft, fire, falling objects and hitting an animal.

Auto Insurance →

What should I do right after a car accident in Texas?

Make sure everyone is safe and call 911 if anyone is hurt. Exchange names, phone numbers, insurance and license plate information with the other driver, take photos of the scene and damage, and report the claim to your insurance company. Then call your agent so they can help you understand next steps.

Auto Insurance →

How do I add my teenager to my car insurance?

Call your agent when your teen gets their learner's permit or license. Insurance companies have different rules on when a teen driver must be listed. Adding a teen usually raises your premium, so ask about good-student and driver-training discounts.

Auto Insurance →

Home and renters insurance

What does homeowners insurance cover in Texas?

A typical homeowners policy covers damage to your house and other structures, your personal belongings, liability if someone is hurt on your property, and extra living expenses if a covered loss forces you to move out while repairs are made. What's covered depends on your policy form and its exclusions.

Home Insurance →

Does homeowners insurance cover hail and wind damage in Texas?

In most of Texas, including the DFW area, yes: wind and hail are usually covered perils. Many Texas policies have a separate wind and hail deductible that's a percentage of your home's insured value, which can be much higher than your regular deductible. Homes on the Gulf Coast may need separate windstorm coverage.

Home Insurance →

How does a percentage wind and hail deductible work?

It's based on your dwelling coverage, not the size of the claim. For example, with a 2% wind and hail deductible on a home insured for $300,000, you would pay the first $6,000 of a covered hail claim. Check your declarations page so you know the dollar amount before storm season.

Home Insurance →

Does homeowners insurance cover flooding?

Flood damage from rising water is covered by a separate flood policy rather than a standard homeowners policy. Flood coverage is available through the National Flood Insurance Program or a private flood insurer, and it usually has a waiting period before it takes effect.

Home Insurance →

Do I need renters insurance if my landlord already has insurance?

Yes, if you want your own things covered. Your landlord's policy covers the building, not your belongings or your liability. Renters insurance helps cover your personal property, your liability if someone is hurt in your home, and extra living costs after a covered loss.

Renters Insurance →

Umbrella and specialty vehicles

What is umbrella insurance and do I need it?

Umbrella insurance is extra liability coverage that kicks in after your auto or home liability limits are used up. People often consider it if they have significant savings or property, a teen driver, a pool, rental property or a higher chance of being sued.

Umbrella Insurance →

Do I need separate insurance for an RV, boat or motorcycle?

Usually, yes. Boats, RVs and motorcycles each have policies built for how they're used, so they're typically insured on their own. Motorcycles are subject to Texas liability requirements just like cars.

Specialty Insurance: RV, Boat, Motorcycle, ATV & UTV →

Does homeowners insurance cover my ATV or UTV?

ATVs and UTVs are usually insured on their own policy, since homeowners insurance is built around your home. A dedicated policy can cover damage, theft and liability, on and off your property.

Specialty Insurance: RV, Boat, Motorcycle, ATV & UTV →

Business insurance

What insurance does a small business need in Texas?

It depends on what you do, but many small businesses start with general liability, property coverage (often bundled in a business owner's policy), commercial auto if they drive for work, and professional liability if they give advice or services. Contracts and leases may also require specific coverage.

Business Insurance →

What's the difference between general liability and professional liability insurance?

General liability covers claims of bodily injury and property damage, like a customer slipping in your store. Professional liability, also called errors and omissions (E&O), covers claims that your advice or professional work caused someone a financial loss.

Professional Liability (E&O) Insurance →

What is a business owner's policy (BOP)?

A BOP bundles general liability and commercial property coverage into one policy, with options like business interruption and equipment breakdown. It's designed for small and mid-sized businesses; eligibility depends on your industry, size and risk.

Business Owner's Policy (BOP) →

Does my personal car insurance cover a car I use for work?

Personal auto policies are designed for personal driving. If a vehicle is owned by the business or used mainly for work, like regular deliveries or hauling equipment, commercial auto insurance is usually the right fit. Ask us how your use is rated.

Commercial Auto Insurance →

What is inland marine insurance?

Despite the name, it covers business property that moves over land: tools, equipment and merchandise in transit or kept at a job site. Contractors and businesses that take equipment off-site often use it.

Inland Marine Insurance →

Does a small business really need cyber insurance?

If you store customer information, take payments or rely on email and computers, cyber insurance is worth a look. It can help pay for data recovery, customer notifications, legal costs and some losses after a breach or ransomware attack.

Cyber Protection Insurance →

Life insurance

What's the difference between term and universal life insurance?

Term life covers you for a set period, such as 10, 20 or 30 years, and is usually the most affordable way to get a large amount of coverage. Universal life is permanent coverage designed to last your lifetime, with flexible premiums and a death benefit you can adjust within policy limits.

Life Insurance →

How much life insurance do I need?

A common starting point is enough to replace your income for the years your family would need it, plus your mortgage, debts and future costs like college. The right amount depends on your situation, so it's worth walking through the numbers with an agent.

Life Insurance →

What happens when my term life insurance ends?

When the level premium period ends, coverage either stops or the premium rises with age each year. Some policies let you convert to permanent coverage without a new medical exam, so check your policy's conversion options before the term runs out.

Term Life Insurance →

Is the life insurance from my job enough?

It depends on your goals. Group life through work is usually a set amount, such as one or two times your salary, and it's tied to that job. Many people add their own policy alongside it so their coverage stays with them.

Life Insurance →

Claims

Who do I call when I need to file an insurance claim?

You can report a claim directly to your insurance company, and you can call our office during business hours at (817) 766-6044. We'll help you start the claim and explain what to expect. The insurance company handles the claim under your policy's terms.

Contact us →

Draft answers for Dan to approve · General information only; coverage depends on your policy · Texas facts per the Texas Department of Insurance · FAQPage schema on the live site

Don't see your question? Ask Fred.

Fred website assistant — interface preview Interface preview · Fred gives general answers. For your policy, our team is a call away.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30

Insurance Resources

Plain answers to real insurance questions, from our Grand Prairie team.

Know who you'll call.

Get a quote or talk through your coverage with our Grand Prairie team.

Get a quote

Or call or text (817) 766-6044 · Mon–Fri 8:30–5:30

Get a Free Insurance Quote

Tell us what you'd like to cover. Our Grand Prairie team will reach out during business hours to go over your options.

What would you like a quote on?

Contact Us

Call, stop by or send us a note. We'll get back to you during business hours.

Call or text

(817) 766-6044

Visit

3758 S Carrier Pkwy, Ste 132
Grand Prairie, TX 75052

Hours

Mon–Fri 8:30 AM – 5:30 PM
Sat–Sun closed · After hours by appointment

Map embed — office location

Privacy Policy

How we collect, use and protect your information.

Terms of Use

The terms that apply when you use this website.

Free 15-Minute Coverage Checkup

How would you like to meet?